

Aggregate mortgage positioning has consequently returned to about average.
The share of mortgages repricing over the subsequent 12 months (including floating debt) peaked last year at 83% – the “shortest” the mortgage book had been in 13 years, he says.
“At the start of this year, that figure had eased to 72% and it is now 64% – pretty much bang on the long-run average.”
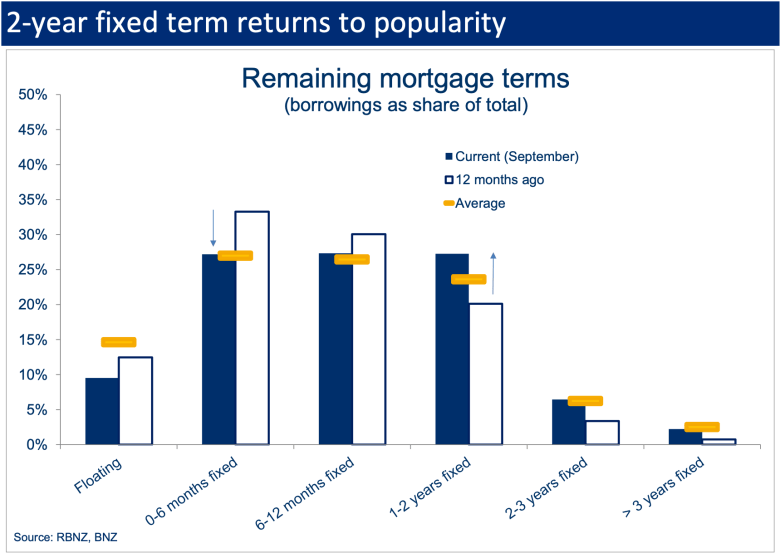
This lengthening in average term mostly reflects the two-year fixed term’s return to popularity.
The share of borrowings with a remaining term of 1-2 years has lifted from below average a year ago to an above average 27%. By contrast, the share of borrowings on floating terms is now the lowest on record at 9.5%.
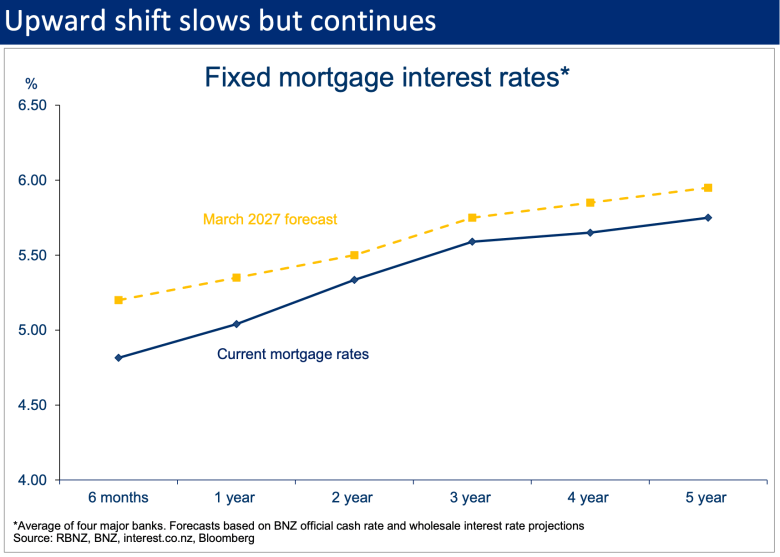
Jones says mortgage borrowers are better protected against rising rates than they were. “But, given where we are in the cycle, we suspect the trend towards longer mortgage terms has a little way to go yet.”
Even if there are a few downward tweaks to mortgage rates in the next few weeks, BNZ chief economist Mike Jones says bank test rates seem less likely to change.
He expects monthly declines in an average range of -0.3 percent a month to continue through to at least year end as political uncertainty has the potential to extend well beyond last Saturday’s election.


Comments
No comments yet.
Sign In to add your comment