
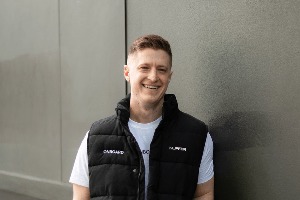
Mortgage advisory, lender, accountancy and insurance company Onboard lending director Ash Mitchell says anyone can enter the business finance industry with no training and ultimately the client and banks are those paying for it.
Mitchell, who has 11 years’ experience in the finance industry, says Onboard frequently sees applications that have been poorly done and it becomes the ambulance at the bottom of the cliff, trying to fix problems. “It costs everyone time and money.”
It is concerning that clients think they're getting good advice when the adviser doesn't understand the products they're selling. There are many products with different cost structures and lending criteria. A significant number of advisers don’t know the costs and can’t explain them to their clients, he says.
In recent examples, Mitchell says a mortgage adviser tried to arrange a 30-year unsecured business loan through the banks, assuming they would offer their client the same rates and structure as home lending when they had no remaining equity. “Not only does this block up the queue of applications and delay other deals, but the client’s expectations were set completely wrong.
“The adviser wasn’t aware of the additional information required to get a business loan approved. On their website they claimed to ‘specialise’ in finance for business owners.”
He says borrowers often contact Onboard while they are in the process of arranging a loan, an application has been in for a month and there has been no decision, or after the fact when problems arise.
“Typically, we get calls from borrowers who have arranged their home loan through a mortgage adviser and then gone back for a business loan. They get poor advice, or loan applications are delayed because they're dealing with an adviser who just doesn't know what they're doing when arranging business loans.”
He recently dealt with a borrower who had approached a mortgage adviser for a line a credit. The borrower believed the loan would be at an interest rate of 15%. “It was 27% because it was a simple rate not an interest rate. The client was oblivious to this. If it had been an unsecured $200,000 overdraft it would have been at 15%, which is relatively normal. When the extra 12% was added to the rate it was extremely expensive.
“There were no steps of advice offered by the adviser to the borrower and no commission disclosure.”
Mitchell says it is ridiculous that there are no advice steps for business products, unlike the steps residential mortgage advisers are bound to take their clients through.
He says while there are some fields, such as asset finance, where a licence is required to sell the products and that diminishes the pool of untrained advisers, there are however, lenders, such as Prospa and BizCap, who allow anyone to sell their products.
“Anybody can set up as a business mortgage adviser. I once had a tradie, who was signed up to do business loans, with no education or training. How is this even possible?
He says a business finance paper, like the residential property lending strand of the Level 5 Certificate in Financial Services residential mortgage advisers must complete before being able to offer advice, needs to be established for business mortgage advisers.
“It won’t completely solve the issue, but it will add at least one barrier so that not every man and their dog can give business lending advice. You shouldn’t be able to label yourself an adviser if you don’t know what you’re advising on.
“If you can't understand the product yourself, how are you supposed to advise your client about whether that product suits them best and whether it's going to help their business?”
He says instead of looking at all the options or giving them proper advice around how they can help, an untrained adviser will just go with the most convenient option, which is typically a cash flow lender, or they might just decline the deal and tell them that there are no business loan products, or they don't actually know what options there are available to the client.”
While Onboard is sometimes able to become involved in a loan application before it is settled, it often gets calls after they settle.
Mitchell says that is difficult. “In some situations, the lender won’t give the borrower more money or restructure the debt when they've just taken on more loans, so we can't really do much.
And a lot of these lenders will have break costs too, so refinancing or restructuring is out of the question. Paying down the loan is often the best option rather than refinancing.”
Comments
No comments yet.
Sign In to add your comment