
Growth in mortgage lending was near zero in May and June – the lowest in three years – and has been static or dropping since then.
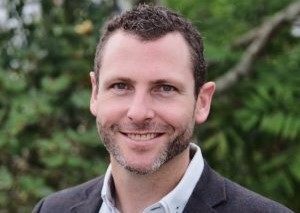
Whangarei-based Key Mortgages director and mortgage adviser Jeremy Andrews says the mortgage sector has been quiet for most of this year and the easiest way to substantiate that is banks' turnaround times.
When mortgage advisers are busy, turnaround times push out to several weeks.
Over the past two years bank turnaround times blew out to an average of 10 working days for standard live deals, with some adviser-submitted applications waiting anywhere from 8 to 15+ working days.
At the end of 2024 high demand was boosted by falling interest rates, refinancing and a surge in property market activity. The same occurred in June last year, with some applications taking up to seven to 28 working days, while at the end of last year banks offered 1.5% cashback driven refinancing resulting in high application volumes, processing delays and an approval bottleneck extending into early this year.
“During times when buyers have FOMO (fear of missing out) and business is pumping, a one week turnaround from a bank is excellent. Now none of the banks are taking that long. They typically have a one to three day turnaround.”
Andrews says this an extremely black and white but easy way to measure how busy things are in the sector, which has been quiet for most of the year.
“Even with changes in legislation encouraging advisers to submit a mortgage application to multiple banks, the turnaround times are still quick.
He says if an adviser can get an application turned around within a day, they probably only need to submit it to one bank to establish a baseline that suits the client and to compare the offer with what other banks might put on the table, whereas in the past when those turnaround times blew out to weeks, the adviser would have to submit it to multiple banks just to meet the property settlement deadline. “You don’t want to be finding out two weeks down the track there is a problem.”
He says the slowdown in the mortgage market is a combination of the huge amount of money pumped into the economy during Covid, the fallout from the cheap money subsidised by the OCR falling to 2.25%, the incentivising of the Brightline rules, the recent oversupply of houses for sale, the constant talk about property prices not rising and how expensive it is to build a new home.
“As the OCR started to rise people also jumped the ditch or have gone elsewhere, but surprisingly, New Zealand’s cash rate is quite a bit lower than Australia’s now.”
This, along with other changes to property tax in Australia, has a resulted in a record number of Australians wanting to buy in New Zealand and Kiwis coming back from across the ditch.
However, the mortgage market slump is also being driven by uncertainty around the election, Andrews says.
He has had plenty of clients sitting on the fence until after the election to see what any of the smaller parties demand in coalition talks. “There are multiple parties with different tax agendas affecting property.”
Whether the mortgage sector improves in terms of profitability after the election comes down to the value of property sales and how much mortgage appetite buyers have, Andrews says.
“There are more options for buyers with low deposits than there have been in the past few years. Low deposits generally means a buyer is going to borrow more even if house prices stay at the existing level or drop a fraction further.”
Values dropping
However, the Banking Association’s latest data shows first home loan buyer loan sizes fell 3.4%.
Of the 72,209 new home loans opened in the first six months of this year, 22.4% were for first home buyers. The average value of a home loan for first home buyers was $506,761.
The 72,209 new home loans was an increase of 2% from 70,811 in the six months at the end of last year and the average value of all new home loans was $355,805, a 9.4% decline.
The overall value of all new home loans opened dropped by 7.6% to $25.7 billion.
More than 62% of loans were on fixed interest rates, 16.3% were on variable rates and the remaining 21.5% were on a mix of fixed and variable rates.
A low 1.2% were behind on their loan repayments, down from 1.4% at the end of last year, while about 42.9% were ahead, unchanged from the end of last year.
Comments
No comments yet.
Sign In to add your comment